Mortgage Blog
Your Guide to a Prime-Linked Variable Rate Mortgage in Canada
September 27, 2026 | Posted by: Matt Shepherd
Understanding the Variable Mortgage Landscape in Burlington
When navigating the housing market in Burlington, ON, choosing the right financing is a critical step. A prime-linked variable rate mortgage (often simply called a Variable Mortgage) offers unique flexibility for homebuyers. As a leading choice for a variable rate mortgage canada, this mortgage type has interest rates that fluctuate in tandem with the Bank of Canada's prime rate. If you are debating between this and a conventional fixed-rate mortgage, understanding the mechanics of a prime-linked setup is essential.
There are two primary structures under the variable umbrella:
- Adjustable Rate Mortgages (ARM): Your monthly payment amount changes as the prime rate goes up or down.
- Discounted Variable Mortgages (VRM): Your monthly payment remains static, but the proportion of your payment going toward the principal versus interest shifts based on the prime rate.
As a local Burlington mortgage broker, I help clients decipher which of these options aligns best with their financial goals.
Adjustable Rate vs. Discounted Variable: What You Need to Know
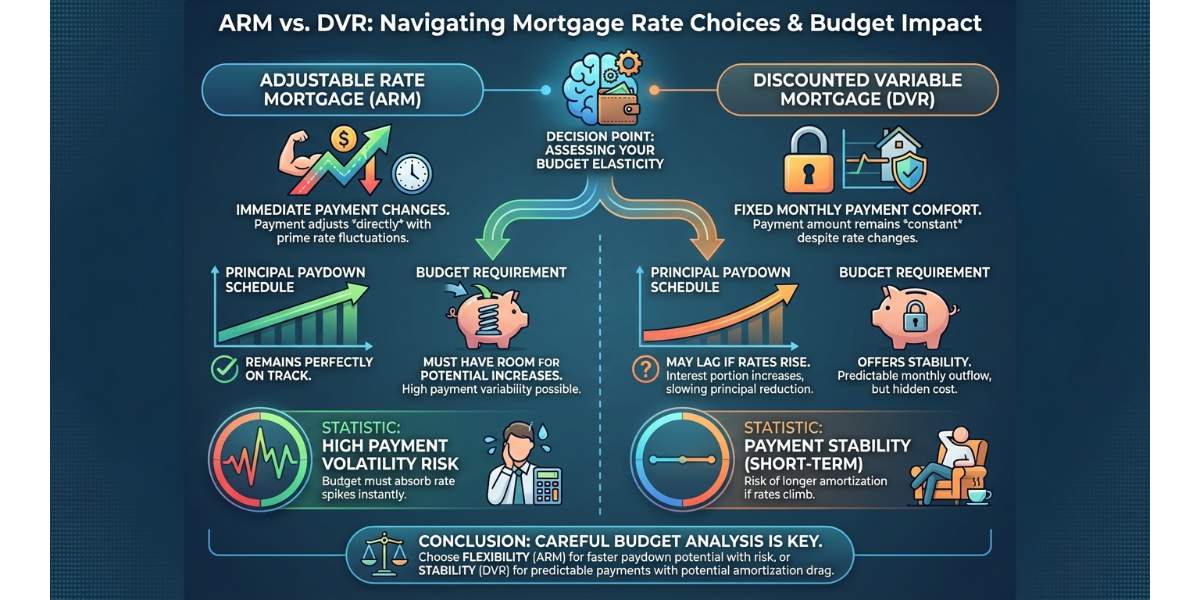
Deciding between an adjustable rate and a discounted variable rate requires a careful look at your monthly budget. With an adjustable rate mortgage, you will see immediate changes to your required payment whenever the prime lending rate adjusts. This means your principal paydown schedule remains perfectly on track, but you need room in your budget for potential payment increases.
Conversely, a discounted variable mortgage offers the comfort of a fixed monthly payment. However, if interest rates rise significantly, you could hit your trigger rate, meaning your payment only covers the interest. In today's dynamic rate environment, having an expert evaluate your specific scenario is crucial. We are experts at providing second opinions on variable-rate mortgages, ensuring you are never caught off guard by changing economic tides.
| Mortgage Type | Payment Structure | Interest Rate Link | Principal Paydown |
|---|---|---|---|
| Conventional Fixed | Static | Locked for term | Predictable |
| Adjustable Rate (ARM) | Fluctuates | Prime-linked | Predictable |
| Discounted Variable (VRM) | Static | Prime-linked | Fluctuates |
Why Get a Second Opinion on Your Variable-Rate Mortgage?
Mortgage rules and lender offerings change frequently. If you currently hold a variable mortgage or are up for renewal, you might be wondering if you are still getting the best possible terms. This is where professional mortgage advice shines. Whether you are in Burlington, Hamilton, Oakville, or Toronto, having an experienced broker review your current setup can save you thousands in interest.
At TLC Mortgage Group, we pride ourselves on transparency and client education. We evaluate your current lender's offer against over 40 different lenders to see if a prime-linked variable rate is still your most advantageous route. If you are feeling uncertain about your current mortgage trajectory, reach out to Jason Woods today.
Compliance Notice: Jason Woods is a Principal Broker with TLC Mortgage Group, License #12988. All financing is subject to approved credit and lender terms.
Q1: What is a prime-linked variable rate mortgage in Canada?
A prime-linked variable rate mortgage is a home loan where the interest rate is tied to the lender's prime rate, which typically follows the Bank of Canada's overnight rate. Your interest costs will rise or fall as the prime rate changes.
Q2: How does an adjustable rate differ from a discounted variable mortgage?
With an adjustable rate mortgage, your actual monthly payment amount changes when the prime rate changes. With a discounted variable mortgage, your monthly payment stays the same, but the amount going toward your principal versus interest adjusts.
Q3: Is a variable mortgage better than a fixed rate mortgage?
It depends on your risk tolerance and market conditions. Variable rates historically cost less over the life of a mortgage, but fixed rates offer peace of mind with predictable payments.
Q4: Can I lock in my variable rate mortgage to a fixed rate later?
Yes, most lenders allow you to convert your variable rate mortgage into a fixed rate mortgage at any time without a penalty, provided you lock in for a term equal to or longer than the time remaining on your current mortgage.
Q5: Why should I get a second opinion on my mortgage?
Lenders do not always offer their best rates upfront to existing clients. A second opinion ensures you are getting competitive terms, the right mortgage structure, and potentially saving thousands of dollars over your term.
Get Your Free Mortgage Second Opinion Today