Mortgage Blog
Your Complete Guide to a Purchase-Plus-Improvements Renovation Mortgage in Burlington
September 13, 2026 | Posted by: Matt Shepherd
What is a Renovation Mortgage in Canada?
If you have found the perfect home in Burlington, ON but it needs a little TLC, a Purchase-Plus-Improvements Renovation Mortgage might be exactly what you need.
Often simply called a Renovation Mortgage, this specialized financing option allows homebuyers to bundle the cost of home improvements into their primary mortgage. Instead of relying on high-interest credit cards or draining your savings after making a down payment, a primary renovation mortgage canada program lets you borrow against the future value of your newly improved home.
Interestingly, this concept is quite similar to the fha-203k-renovation-loan USA buyers use south of the border. Whether you are looking at properties in Hamilton, Oakville, or right here in Burlington, securing this type of loan means you can upgrade that dated kitchen or finish the basement immediately after moving in.
As a principal broker at TLC Mortgage Group, I specialize in providing second opinions on purchase-plus-improvements and renovation mortgages to ensure you get the absolute best terms available.
CMHC Purchase Plus and Bank-Specific Add-Ons
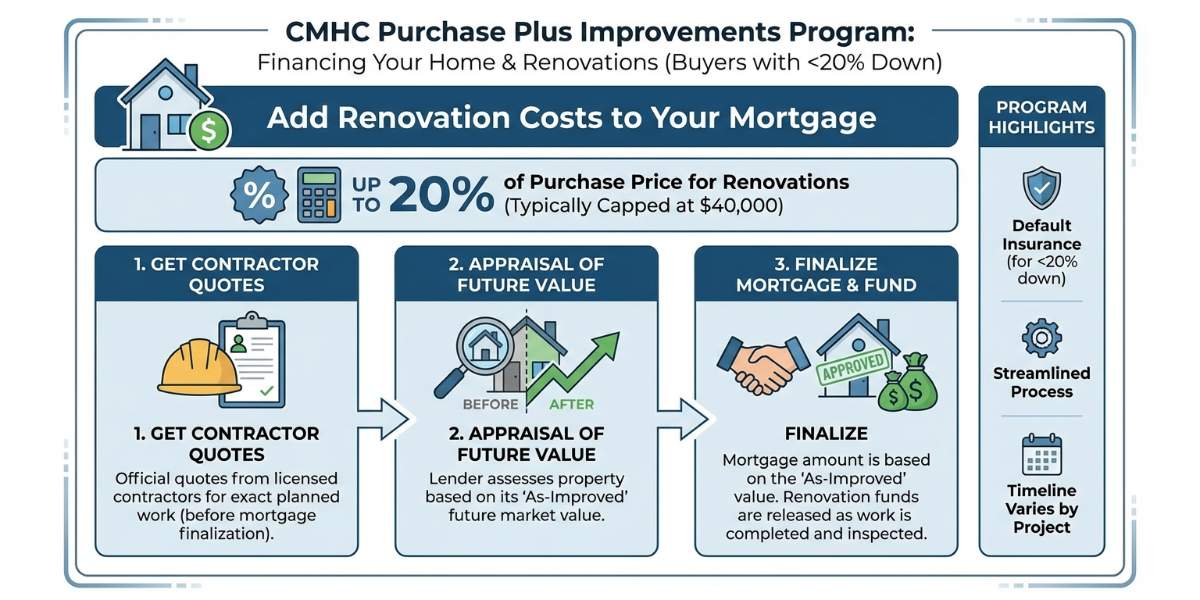
The most popular program for buyers with less than a 20 percent down payment is the CMHC Purchase Plus Improvements program. This default insurance program allows you to add up to 20 percent of the home purchase price (typically capped at $40,000) for renovations.
- Get Contractor Quotes: Before your mortgage is finalized, you must provide official quotes from licensed contractors for the exact work you plan to do.
- Appraisal of Future Value: The lender will assess the property based on its as-improved value.
- Funds Held in Trust: The renovation funds are advanced to your lawyer and held in trust until the work is completed and officially inspected.
Beyond CMHC, many lenders offer unique bank-specific add-ons. Some financial institutions have proprietary renovation mortgage products that might allow for higher limits or more flexible draw schedules if you have a larger down payment. If you are exploring mortgage refinancing to fund a project, these bank-specific rules can vary greatly. That is why getting an expert second opinion is crucial to saving money and avoiding stressful delays.
| Feature | Standard Mortgage | Purchase-Plus-Improvements |
|---|---|---|
| Renovation Funding | Not included | Built into the primary mortgage |
| Interest Rate | Standard low mortgage rates | Standard low mortgage rates |
| Down Payment Basis | Based on current purchase price | Based on as-improved value |
| Fund Release | On closing day | After renovations are verified |
Why Get a Second Opinion on Your Renovation Mortgage?
Navigating the requirements of a renovation mortgage in Canada can be complex. From managing contractor quotes to understanding lender-specific payout structures, the details matter immensely. If you have already been pre-approved by a bank, getting a second opinion from an experienced mortgage broker can uncover hidden fees or reveal better rate options.
With access to over 40 lenders, I can help you compare CMHC Purchase Plus policies against alternative bank-specific add-ons. My goal is to ensure your financing is fast, simple, and secure. Whether you are a first-time home buyer or an experienced investor looking to upgrade a property in Burlington, I am here to guide you through every step.
Q1: What is a Purchase-Plus-Improvements mortgage?
It is a specialized mortgage that allows homebuyers to add the estimated cost of renovations to their total mortgage amount, rather than paying out of pocket after closing.
Q2: How much can I borrow for renovations under the CMHC program?
Generally, you can borrow up to 20 percent of the purchase price or $40,000, whichever is less. However, bank-specific add-ons may offer different limits depending on your down payment.
Q3: Can I do the renovation work myself?
Most lenders require the work to be completed by licensed contractors to ensure the quality of the improvements matches the projected as-improved appraisal value.
Q4: When do I actually get the money for the renovations?
The renovation funds are typically given to your lawyer on closing day and held in trust. They are only released to you to pay your contractors once an appraiser verifies the work is 100 percent complete.
Q5: Do you offer second opinions on existing renovation mortgage approvals?
Yes, we are experts at providing second opinions on purchase-plus-improvements and renovation mortgages to ensure you are getting the best rates and the most favorable terms for your project.
Contact Jason Woods Today for Your Free Renovation Mortgage Consultation